Protect The Buildings And Contents Behind Your Business
Commercial property insurance can help pay to repair or replace the building, equipment and stock your business depends on. We compare carriers for Nebraska owners and explain your choices in plain words.
What Commercial Property Insurance Means For Nebraska Businesses
Commercial property insurance pays for damage to the physical things a business owns or uses. That usually means the building, fixtures, equipment, furniture and stock. It responds when a covered event, such as fire or hail, causes a loss.
Anyone who owns a building, rents space, or keeps tools and inventory on site can need this coverage. A landlord insures the structure. A tenant often insures what is inside. Your lease may spell out who covers what.
A policy can include business personal property insurance for contents, plus coverage for outdoor signs, and sometimes extra expense after a loss. Common exclusions include flood, earthquake and normal wear. Those depend on your policy and carrier.
We are an independent agency, so we can ask several carriers for terms instead of selling one policy. We walk through limits, deductibles and exclusions with you, and we answer questions before you decide.
What A Property Policy Can Include
Every policy is written a little differently. These are the parts business owners ask about most often. What applies to you depends on your policy and carrier, so we read the details with you.
Buildings And Structures
This part can pay to repair or rebuild the building you own, along with permanent fixtures and attached structures, after a covered loss such as fire, wind or hail.
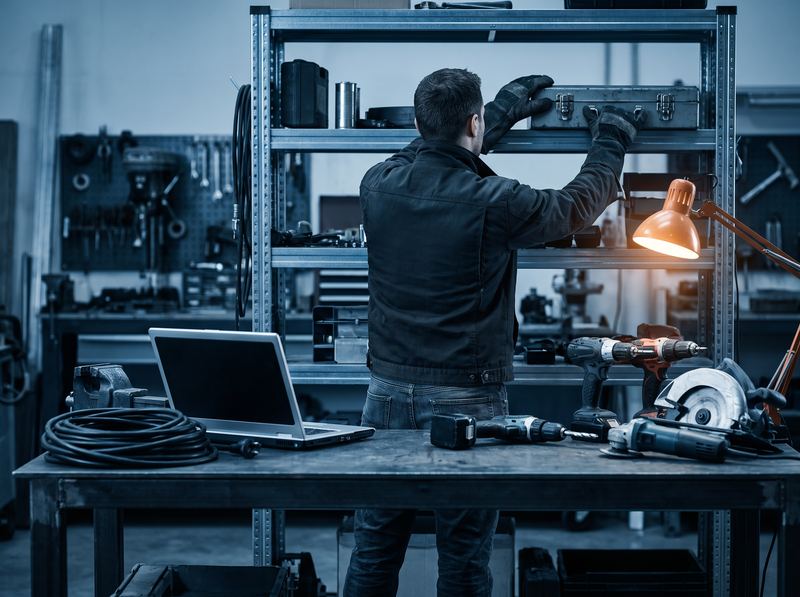
Equipment And Stock
Business personal property coverage can help replace machinery, tools, furniture, computers and inventory when a covered event damages or destroys them.
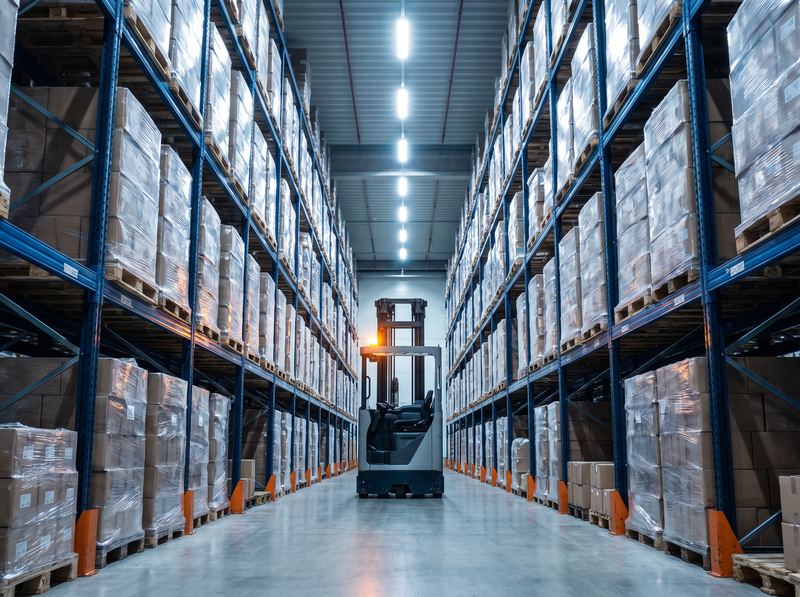
Stored Inventory
If you keep goods in a storage building or warehouse, the policy can include them. We check how the policy values stock and where it must be kept.
Lost Income After A Loss
Some carriers offer business income coverage that can help pay ongoing bills while a covered loss keeps you closed. It is a separate part of the policy that we can add.
Independent Means Choices
We work with many insurance carriers, so we can compare commercial property insurance options for coverage, service and price. Everyone does not get the same policy.
Coverage
Carriers define covered perils and exclusions in different ways. Because we work with many carriers, we can show you how each one treats the risks your building faces.
Service
We explain the policy language in plain words, help you understand deductibles and limits, and stay your contact when you have a question about your property coverage.
Price
Carriers rate buildings differently, so premiums can vary from one to the next. We gather quotes side by side so you can weigh cost against the protection offered.
What We Ask Before We Shop Carriers
Before we ask carriers for quotes, we learn how your property is built and used. Age, construction and location can shape what carriers offer. Accurate answers help avoid surprises when you file a claim.
We also look at what you would need to rebuild or replace. Many owners underestimate that figure. A policy that falls short can leave you paying the gap yourself, so we talk it through.
- Building age and construction type
- Value of equipment and stock
- Whether you own or rent
- Past losses and current protection
- Lender or lease insurance requirements
Tell Us About Your Business
We will find out more about your Nebraska commercial insurance needs, compare carriers and come back with options.
- 1 Tell Us What You Do
- 2 We Compare Carriers
- 3 We Come Back With Options