Look After Your Team If Someone Gets Hurt On The Job
Workers compensation insurance can help pay medical care and part of lost wages when an employee is hurt at work. We compare carriers for Nebraska employers, including small business owners, and explain the details.
Workers Compensation Insurance For Nebraska Employers
Workers compensation insurance is a business policy. It can help pay for medical care and part of lost wages when an employee is hurt or made ill by the job. It is usually no-fault.
Most employers with staff can need it, since state law often requires it. Small businesses need it too, because even a small crew can face a bad injury. Rules on owners and contractors vary.
A policy usually covers medical care, part of missed pay, rehab and death benefits. It can add employer's liability cover. It usually does not cover your property or customer injuries. Details depend on your policy and carrier.
We are an independent agency. We can ask several carriers for workers comp quotes for your business. We explain how job classes and payroll affect the policy.
What A Workers Comp Policy Can Include
Workers compensation has a few main parts that work together. Exact benefits are set by state law and your policy, so we read the details with you.
Medical Care For Injuries
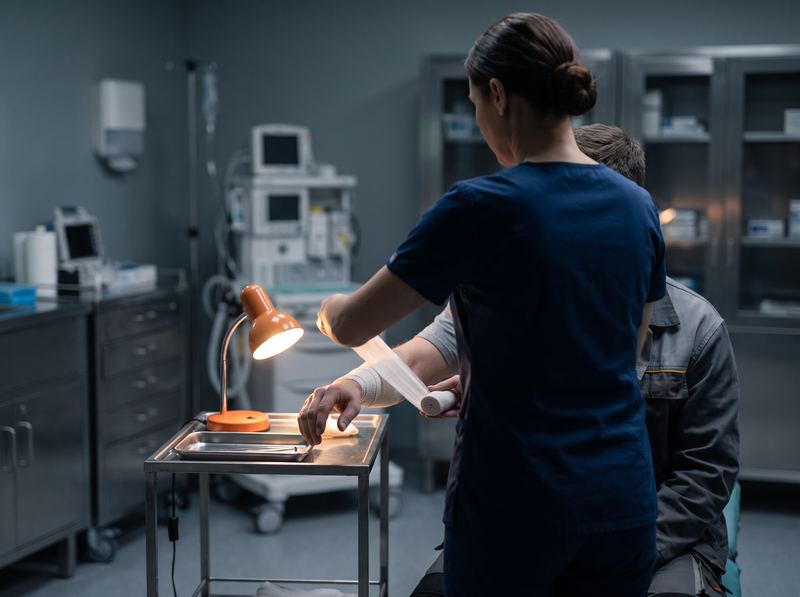
The policy can help pay for doctor visits, hospital care, medicine and therapy when an employee is hurt on the job and the claim is accepted.
Part Of Lost Wages
When an injury keeps someone off work, benefits can replace part of their pay for a time. The amount and length follow state rules and your policy terms.
Safer Workplaces
Many carriers provide safety resources, and fewer claims can help over time. We can talk about practical steps that fit the way your crew works.
Employer Liability Protection
Employer's liability coverage can help if an injured worker's family sues your business. It is often part of the same policy, and we explain how it works.
Independent Means Choices
We work with many insurance carriers, so we can compare workers' compensation insurance options for coverage, service and price. Everyone does not get the same policy.
Coverage
Carriers differ in the programs, safety services and optional features they offer. We can compare those terms for your industry and staff.
Service
We help you report payroll in plain terms, explain how audits usually work, and stay available when you have a question about a claim or a certificate.
Price
What a policy costs depends on payroll, job classifications and claims history, and each carrier rates them differently. We gather quotes so you can compare them side by side.
What We Ask Before We Shop Carriers
We start with who works for you. Employees, owners, part-time staff and subcontractors can be treated differently. We ask how many people you have and what each does.
Payroll and job duties drive the policy. We ask for your payroll by role and your past claims. This helps carriers class the work right, so an audit holds no surprises.
- Number of employees and their roles
- Estimated payroll for each job class
- Use of subcontractors or temporary help
- Past injuries and claims history
- Safety practices and training in place
Tell Us About Your Business
We will find out more about your Nebraska commercial insurance needs, compare carriers and come back with options.
- 1 Tell Us What You Do
- 2 We Compare Carriers
- 3 We Come Back With Options